Tax Residency Certificate Apostille

GOOD APOSTILLE SERVICES provides professional Tax Residency Certificate Apostille assistance for individuals and businesses preparing their certificates for official use abroad.

call us

+91 7016754663

call us

+91 9824692246

Tax Residency Certificate Apostille services for overseas document use
Tax Residency Certificate Apostille
01

When Is Tax Residency Certificate Apostille Required?

An Indian TRC may need an apostille when a foreign tax authority, bank, payer or business counterparty requests authenticated proof of Indian tax residence. Tax Residency Certificate Apostille is relevant only when the destination accepts Hague Apostilles and the recipient specifically requires one. For broader authentication needs, see our document apostille services guidance.

  • DTAA or treaty-relief submissions
  • Foreign tax authority filings
  • Cross-border payment documentation
  • Banking or KYC compliance
  • Overseas corporate registrations
  • Recipient-requested document authentication
Confirm the destination and receiving authority first; not every overseas use requires an apostilled TRC.
02

What Does an Apostille for Tax Residency Certificate Verify?

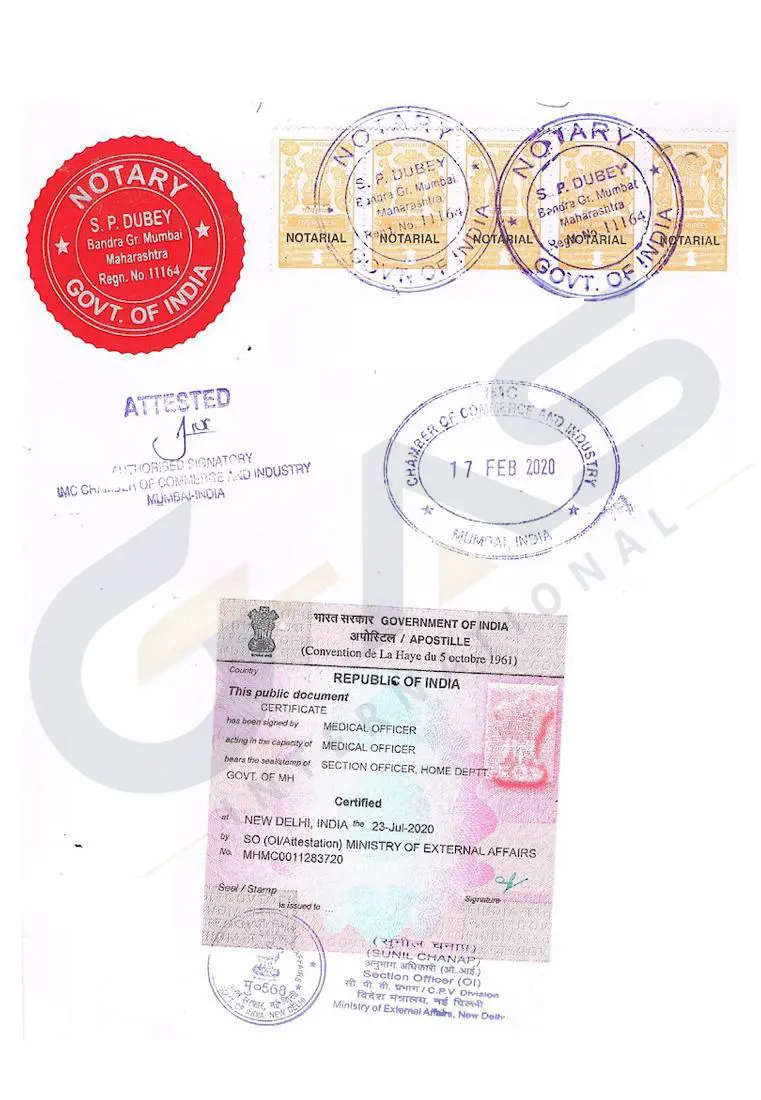
An apostille authenticates the origin of the TRC; it does not decide treaty eligibility or tax liability. It verifies the signature, the signer's official capacity and, where applicable, the seal or stamp. For a destination that does not accept apostilles, check the applicable Tax Residency Certificate attestation route.

  • Signature authenticity on the TRC
  • Official capacity of the signer
  • Identity of seal or stamp
  • Country of document origin
  • Apostille issue place and date
  • Competent authority and certificate number
An apostille authenticates document origin; it does not certify the TRC's tax conclusions.
03

Tax Residency Certificate Apostille Services: Process and Timing

Timing depends on whether the TRC is ready for authentication, whether prior verification is required and which MEA route applies. e-Sanad can be used only where the document is available through an integrated digital repository; other documents follow the applicable pre-authentication and authorised submission process.

  • Correct TRC residency period
  • Readable signature and seal
  • e-Sanad repository availability
  • Required pre-authentication steps
  • Authority processing time
  • Collection and return delivery
MEA's Citizen's Charter says processing is usually within seven working days after receipt in MEA; earlier verification and courier time are additional.
04

Documents Needed for MEA Apostille for Tax Residency Certificate

Use the final TRC issued for the required period. Under the 2026 income-tax framework, an Indian resident applies in Form 42 and the Assessing Officer issues Form 43; older guidance may refer to Forms 10FA and 10FB. Offline MEA processing generally also requires the original or eligible true copy, a document photocopy and the applicant's passport photocopy.

  • Issued Form 43 TRC
  • Original or eligible true copy
  • Clear document photocopy
  • Applicant passport photocopy
  • Required prior authentication
  • Foreign recipient instructions
Do not submit Form 42 instead of the issued TRC unless the foreign recipient specifically asks for the application.

Tax Residency Certificate Apostille: Practical Commercial Document Guidance

TR

Tax Residency Certificate Document Apostille Readiness

Before submission, check that the TRC is the final certificate issued for the required period and that the taxpayer name, status, address, PAN, issuing authority, signature and seal are readable. A mismatch between the TRC and the foreign recipient's records can cause avoidable queries even when the apostille itself is correctly issued.

  • Correct taxpayer or entity name
  • Correct tax year or residency period
  • PAN and address details checked
  • Issuing officer details clearly visible
  • Signature and seal readable
  • Foreign recipient requirement confirmed
FX

Where an Apostilled Tax Residency Certificate Is Used

An apostilled TRC may be requested when an Indian resident or entity needs authenticated evidence of tax residence for a foreign tax authority, payer, bank or compliance team. The underlying purpose is usually treaty, withholding, remittance or cross-border documentation; the exact requirement should always come from the overseas recipient.

  • Foreign tax authority submissions
  • DTAA and treaty-relief documentation
  • Reduced withholding support
  • Cross-border banking or remittance files
  • Corporate compliance and KYC
  • Overseas business registrations
CD

Commercial Documents Related to Tax Residency Apostille

A TRC may be submitted alongside other business records in an overseas tax, regulatory or commercial file. Related records can have separate authentication requirements, so verify each document individually instead of assuming one apostille covers the full file. Tax registrations, product certificates, incorporation records and commercial agreements may each follow their own document-specific verification route.

Read More

Tax Residency Certificate Apostille FAQs

Current answers on TRC eligibility, Form 42 and Form 43, apostille requirements, MEA processing, fees, verification and document handling.

Tax Residency Certificate Apostille Basics

When a TRC needs authentication and what an apostille actually proves.

A Tax Residency Certificate is issued by the Indian Income Tax Department to confirm Indian tax residence for a stated period. An overseas recipient may ask for an apostille when authenticated proof is required.

The apostille confirms the signature, the signer's official capacity and, where applicable, the seal or stamp. It does not validate the TRC's tax conclusions or grant treaty benefits.

No. The Apostille Convention must apply between India and the destination, and the receiving authority must actually require an apostille. Non-Convention destinations may use a different legalisation route.

Tax Residency Certificate Documents

Which certificate to submit and what details should be checked first.

Submit the final certificate issued for the required period. Under the 2026 framework, resident taxpayers apply in Form 42 and the Assessing Officer issues the residence certificate in Form 43.

Check the taxpayer name, status, PAN, address, tax year or period, issuing authority, signature, designation and seal. The information should match the records being presented to the foreign recipient.

For offline MEA submission, the original document or eligible true copy, a photocopy of the document and a photocopy of the applicant's passport are generally required. Prior authentication may also apply.

MEA Tax Residency Certificate Apostille Process

Practical steps from document review through MEA apostille verification.

First confirm the destination requirement, then identify the applicable verification route. Complete any required pre-authentication, submit through the authorised channel, obtain the MEA apostille and verify the issued certificate after return.

MEA's Citizen's Charter states that apostille is usually completed within seven working days after receipt in MEA. Pre-authentication, document collection, verification and return courier can extend the overall turnaround.

Use the e-Register on the e-Sanad portal and enter the Apostille or Attestation Number shown on the certificate. Application status can separately be checked with an Application ID or Document ID.

Tax Residency Certificate Apostille Fees & Timing

Official MEA charges, variable service costs and realistic timing factors.

MEA lists a government fee of ₹50 for each apostilled document. Service-provider, scanning, pre-authentication, pickup or courier charges are separate where applicable.

The total depends on the required verification route, number of documents, authorised service-provider charges, scanning, collection and return delivery. A written quotation should separate these items clearly.

No. Obtaining the TRC from the Income Tax Department and obtaining an apostille from MEA are separate processes. Any charges or requirements for one should not be assumed to cover the other.

Tax Residency Certificate Pickup & Delivery

Safe handling of original or eligible hard-copy documents.

Pickup availability depends on courier coverage and the selected service arrangement. Before handing over a TRC, confirm the collection address, document count, packaging method, charges and tracking details.

Keep the TRC flat in a protective waterproof sleeve and rigid envelope. Avoid folding, stapling, laminating or marking it, and retain a clear scan plus the courier receipt before dispatch.

Check that the apostille is attached to the correct TRC, review the certificate number and issue details, verify it through the e-Register, keep a scanned copy and send only the format requested by the overseas recipient.

Need Apostille or Attestation Support for Your Documents?

Your Trust, Our Responsibility — That’s a G-AS Commitment.

call us

+91 7016754663

call us

+91 9104499727

whatsapp

+91 9824692246

Email us

info@goodapostille.com

Our Apostille Process

01

Document Review

We check the document, purpose and destination country.

02

Route Confirmation

The correct verification route is confirmed before submission.

03

Authority Verification

Required verification is completed through the relevant authority.

04

MEA Apostille

The eligible document proceeds for final apostille processing.

05

Secure Delivery

Completed documents are checked, packed and safely dispatched.